How Much Home Can You Afford — DHA Lahore
Every field, the formula behind it, and a worked example.
Last updated:
Help › The calculators › Affordability
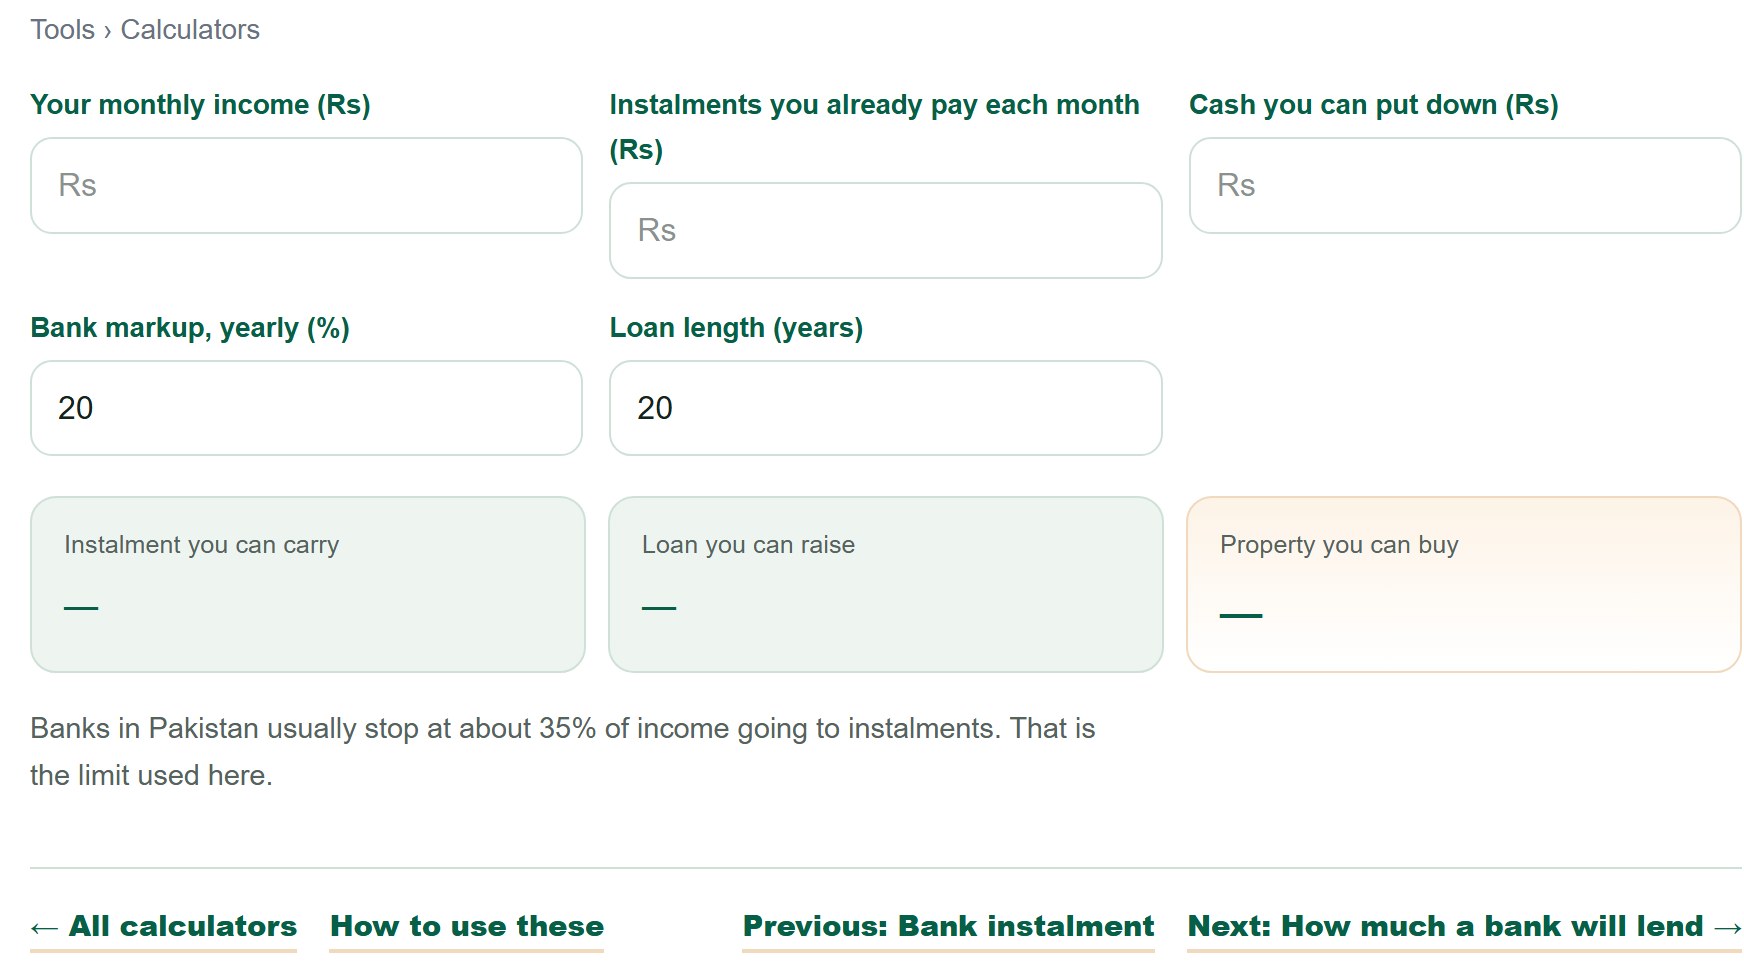
Takes your monthly income, the instalments you already pay, the cash you can put down, and the bank's markup — and works back to the price of house you can actually buy.
 Open this calculator
01
When to use it
Use it before you start looking, not after. Knowing your ceiling saves you from falling in love with a plot that was never within reach.
02
Every field, explained
| Your monthly income (Rs) | What reaches your hand every month, after tax. If two people are buying together, add both incomes — a bank will. |
| Instalments you already pay each month (Rs) | Car instalment, an existing loan, a committee — anything that is already booked. This is subtracted first, because the bank subtracts it first. |
| Cash you can put down (Rs) | Your own money, not borrowed. This is added to the loan at the end, and it is the part that decides whether the whole thing works. |
| Bank markup, yearly (%) | The rate the bank charges, per year. It starts at 20 because that is a common figure in Pakistan today — replace it with the number your own bank quotes. |
| Loan length (years) | How long you will keep paying. Longer means a smaller instalment but much more total markup. Starts at 20. |
03
How the answer is worked out
- First it takes 35% of your income — that is roughly where banks in Pakistan stop — and subtracts the instalments you already pay. What is left is the instalment you can carry.
- Then it works backwards from that instalment, at the markup and the number of years you gave, to the size of loan that instalment would service.
- Finally it adds your down payment. That total is the property price you can look at.
A worked example
| Monthly income | Rs 400,000 |
| Instalments already paid | Rs 50,000 |
| Cash down | Rs 1 crore |
| Markup / years | 20% / 20 years |
| Instalment you can carry | 400,000 × 35% − 50,000 = Rs 90,000 |
That instalment supports a loan of roughly Rs 52 lakh, so with your 1 crore down you are looking at property around Rs 1.5 crore — a 5 marla plot in several phases, but not 10 marla in Phase 6.
04
Mistakes people make
- Entering income before tax and deductions. Use what actually arrives.
- Forgetting the instalments already running. They come off the top.
- Treating the answer as the price of the house. Transfer cost and taxes are on top of it — the transfer calculator is for that.
- Leaving the markup at 20% without asking your own bank. Two points of difference moves the answer by lakhs.
05
What it does not do
- It is not a bank approval. A bank also looks at your age, your job, your record and the property itself.
- It does not include transfer cost, taxes, or the money a house needs after you buy it.
- It assumes the markup stays the same for the whole term. In Pakistan it usually does not.
- It does not know today's plot prices — for that, open the market report.
06
Questions
- Why 35%?
- Is my data sent anywhere?
- Can I use it for a plot instead of a house?
Because that is roughly the ceiling most banks in Pakistan use for how much of your income can go to instalments. It is a limit, not a target — living at 35% is uncomfortable.
No. Every one of these calculators runs inside your own browser. Nothing is stored and nothing is sent to us.
Yes, but remember banks lend far less readily against bare plots than against built houses.